
GHANA INFLATION RISES TO 5.2% IN SEPTEMBER AS NON-FOOD PRICES DRIVE SECOND STRAIGHT INCREASE
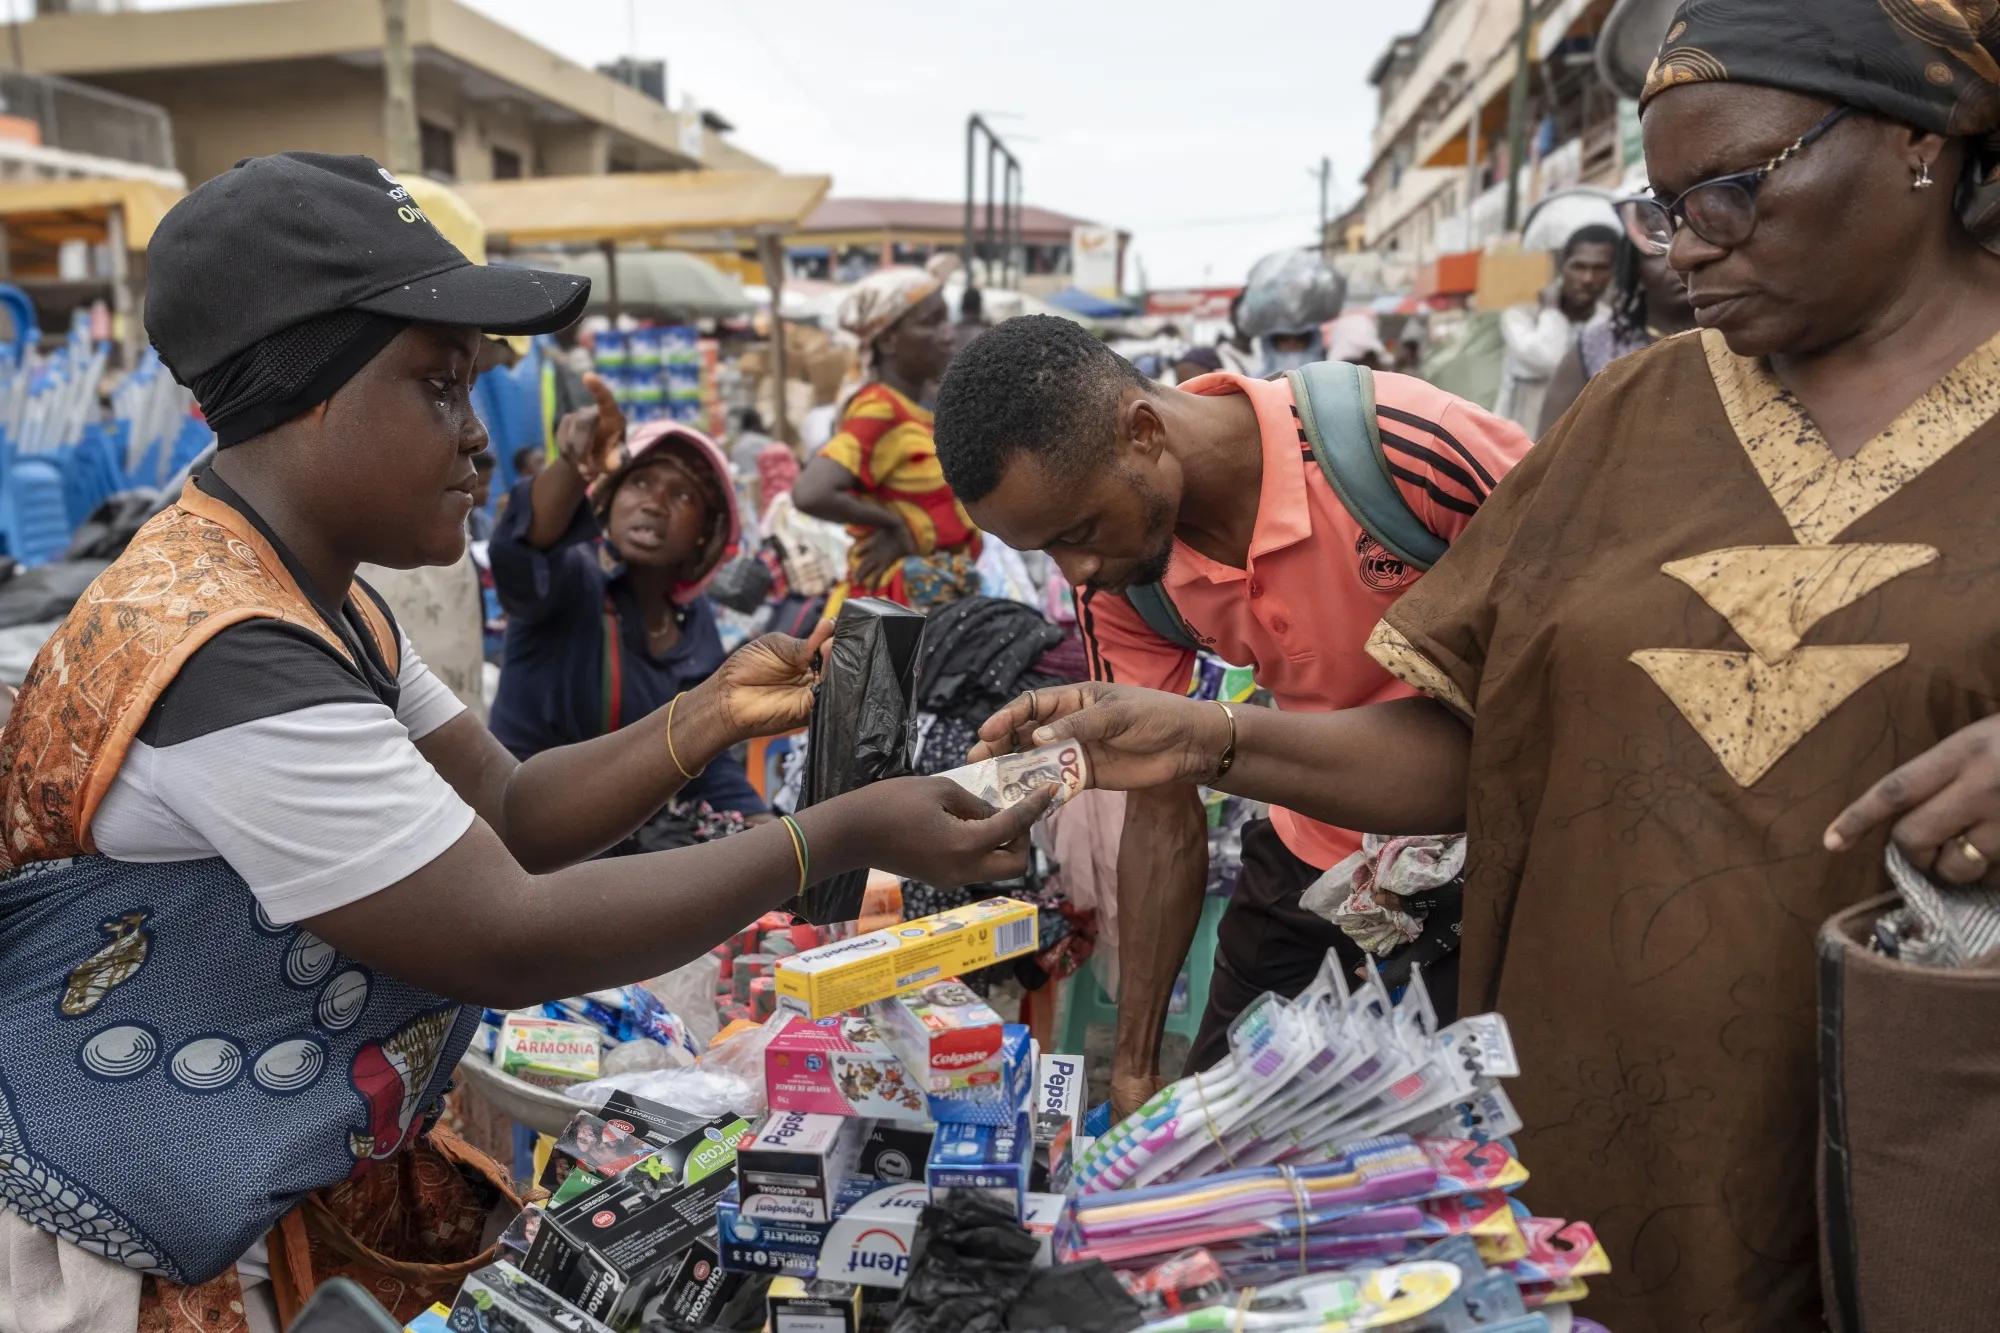
Ghana’s annual inflation increased to 5.2 percent in September from 5.0 percent in August, marking a second consecutive monthly acceleration after inflation reached 4.6 percent in July. Non-food inflation of 6.2 percent was the main driver, while food inflation stood at 4.0 percent.
Ghana’s annual consumer inflation rose to 5.2 percent in September from 5.0 percent in August, extending an emerging upward movement in prices for a second consecutive month after inflation reached 4.6 percent in July. The latest figures from the Ghana Statistical Service show that the country remains in a comparatively low-inflation environment after the sharp declines recorded over the past year, but the September reading confirms that the downward trend has paused and that domestic price pressures are beginning to rebuild.
Government Statistician Alhassan Iddrisu said non-food inflation was the principal driver of the September increase, with prices in that category rising 6.2 percent from a year earlier compared with food inflation of 4.0 percent. Non-food items now account for nearly two-thirds of overall inflation, shifting the character of Ghana’s price pressures away from the food-led inflation that dominated much of the country’s recent cost-of-living crisis.
The new figures are important because they represent a second consecutive monthly acceleration after inflation fell to 4.6 percent in July. It rose to 5.0 percent in August before moving another 0.2 percentage points higher in September. The increases remain modest compared with the extreme inflation Ghana experienced during the economic crisis, but the change in direction is being closely watched by the Bank of Ghana, businesses and households because it may indicate that some of the forces that pushed inflation sharply lower are beginning to lose momentum.
Inflation has almost halved over the past year, reflecting the effects of a more stable currency, tighter monetary conditions, fiscal consolidation and easing price pressures across several important categories. The latest data do not reverse that broader improvement. A 5.2 percent annual inflation rate remains far below the levels Ghana experienced when consumer prices were rising by more than 50 percent annually during the height of the economic crisis.
The September reading nevertheless shows that price stability cannot be assumed simply because inflation has fallen dramatically. Inflation measures the rate at which prices are increasing rather than whether prices themselves have returned to previous levels. A lower inflation rate means the cost of goods and services is rising more slowly, but many households may still be paying substantially more for food, rent, transport and other essentials than they were several years ago.
That distinction is particularly important for ordinary consumers. Ghana’s inflation rate can fall from double digits into low single digits while households continue to feel financial pressure because salaries and household incomes do not automatically recover the purchasing power lost during earlier years of rapid price increases. The September increase therefore adds another reason for policymakers to focus not only on the headline inflation figure but also on the composition of price changes and their effect on different groups of consumers.
The most notable feature of the latest report is the widening difference between food and non-food inflation. Food inflation stood at 4.0 percent, while non-food inflation reached 6.2 percent. That means the pressure pushing the overall index higher is increasingly coming from services and non-food goods rather than from the food basket alone.
This represents a significant shift from earlier phases of Ghana’s inflation problem, when food prices were among the most important drivers of the national rate. Rising prices for locally produced food, imported commodities, transport and agricultural inputs contributed heavily to household costs during the crisis period, particularly as the cedi weakened sharply against major international currencies.
The current picture is different. Approximately 86 percent of Ghana’s inflation is now being generated by goods and services produced domestically, according to the statistical service’s September presentation. That suggests external price pressures and imported inflation have become less dominant than they were during periods when currency depreciation was transmitting rapidly into the cost of imported products.
The Ghana Statistical Service described the current inflation environment as increasingly “home-grown” and driven by services, an important development for economic policy because domestic inflation can be more persistent than price pressures caused mainly by temporary movements in imported goods.
When imported inflation falls because a currency strengthens, the effect can feed relatively quickly through some categories of consumer prices. Services inflation, however, is often influenced by wages, rent, utility costs, transport, business operating expenses and expectations about future prices. Those factors can be more resistant to rapid changes and may require a longer period of stable economic conditions before they fully moderate.
The latest figures will therefore be studied closely by the Bank of Ghana, which kept its Monetary Policy Rate unchanged at 14 percent during its September meeting. The central bank had already noted that inflation had risen from 4.6 percent in July to 5.0 percent in August and said emerging price pressures were beginning to appear even though underlying inflation remained broadly contained.
The bank’s official medium-term inflation target is 8 percent, with a tolerance band of plus or minus 2 percentage points. That means the formal target range runs from 6 percent to 10 percent. At 5.2 percent, September inflation remains below the lower end of that band.
The Bank of Ghana has nevertheless said it expects inflation to move back into the 6 percent to 10 percent target range over the coming quarters. The September increase is consistent with that outlook, although one additional monthly reading is not enough on its own to establish how quickly inflation will rise or where it will eventually stabilize.
The central bank’s decision to hold the policy rate at 14 percent for a third consecutive meeting reflects the balance officials are trying to maintain. Inflation has fallen sharply enough to give policymakers more room than they had during the crisis, but global energy prices and other external risks have become more difficult, while domestic non-food inflation is beginning to rise.
A premature reduction in interest rates could increase borrowing and demand before inflation is firmly stabilized, potentially creating renewed price pressure. Keeping rates high for too long, however, can increase the cost of credit for households and businesses and constrain investment. The latest inflation figures will therefore become one of several pieces of information considered when the Monetary Policy Committee next assesses its stance.
Global conditions add another layer of uncertainty. Crude oil prices have recently traded above $100 per barrel as geopolitical tensions affect energy markets, and Ghana remains exposed to international petroleum prices even when the cedi is relatively stable. Higher fuel costs can eventually affect transport fares, logistics, electricity generation and the cost of moving goods across the country.
Those effects may not appear immediately in the consumer inflation figures. Businesses can absorb some increases temporarily before passing them on to customers, while regulated prices may change according to review schedules rather than in real time. That means international energy shocks can continue filtering through the economy for several months.
Ghana’s currency will also remain important. One of the major reasons inflation declined so sharply from its crisis-era highs was the stabilization and recovery of the cedi, which reduced the local-currency cost of many imported goods and helped improve inflation expectations. A significant weakening of the currency would risk reversing part of that progress by raising the cost of fuel, machinery, medicines, food imports and other products priced internationally.
The government’s fiscal position is another factor. Ghana has been implementing reforms following its debt crisis and restructuring process, with authorities emphasizing tighter budget management and improved public finances. Fiscal consolidation can help control inflation by reducing excessive government demand and easing pressure on domestic financing markets.
Maintaining that discipline will become more important if inflation continues rising. A combination of increased government spending, higher energy prices and weaker exchange-rate conditions could make it more difficult for the central bank to keep price pressures contained.
For businesses, the September data present a mixed picture. Low single-digit inflation offers far greater predictability than the conditions companies faced during Ghana’s recent economic crisis, when rapidly changing prices made budgeting, inventory management and investment decisions extremely difficult. Businesses can plan more effectively when input costs and consumer prices are moving gradually rather than increasing at double-digit rates.
At the same time, the rise in non-food inflation suggests that operating costs are beginning to increase in parts of the economy. Services businesses can be particularly sensitive to changes in wages, rent, utilities, transport and professional costs. If those expenses continue rising, companies may eventually increase prices to protect profit margins.
Consumers may experience the September increase differently depending on their spending patterns. Food inflation of 4.0 percent is relatively moderate by recent Ghanaian standards, but food makes up a larger share of household expenditure for lower-income families. Even small increases can therefore have a disproportionate effect on people who spend most of their income on basic necessities.
Higher-income households may be more exposed to changes in services, housing, transport, recreation and other non-food categories. The national headline rate combines all of those spending patterns into a single average, which means the inflation experienced by an individual household can differ considerably from the published figure.
The same applies across regions. Prices do not move at exactly the same rate throughout the country, and regional inflation can vary because of transportation costs, local supply conditions, housing markets and differences in consumer spending. The national rate is therefore useful for understanding the overall economy but cannot fully describe the cost-of-living situation in every part of Ghana.
September’s increase is also notable because it comes after one of the most dramatic disinflation periods in Ghana’s recent economic history. Inflation reached levels above 50 percent during the worst period of the crisis before beginning a sustained decline as monetary policy tightened, the currency stabilized and government reforms took effect.
That decline played an important role in restoring confidence in the economy. Lower inflation reduces uncertainty, protects real household income from rapid erosion and can eventually allow interest rates to fall if policymakers believe price stability is sustainable.
The difficulty is that disinflation rarely continues indefinitely. Once temporary factors that pushed inflation lower have passed through the data, the rate can begin to stabilize or move modestly upward toward a central bank’s long-term target. Ghana’s July-to-September pattern may represent such a normalization rather than the beginning of another major inflation surge.
The Bank of Ghana’s own forecasts point in that direction. Policymakers have said inflation is likely to return gradually toward the official target band rather than remain permanently below 6 percent. A movement from 4.6 percent in July to 5.2 percent in September is consistent with that expected adjustment, provided the increases remain controlled.
The key question will be whether the acceleration remains gradual or becomes broader and faster.
A sustained rise in non-food inflation would be one warning sign because services and domestically generated prices can be more difficult to reverse. Another would be a renewed rise in food inflation, particularly if poor harvests, transportation problems or currency weakness increase the price of staple foods.
Energy prices will also be closely watched. Ghana imports significant quantities of petroleum products, and changes in international oil markets can affect domestic fuel prices. If crude oil remains above $100 per barrel for an extended period, the effect could eventually feed into transport and production costs.
The cedi’s performance will be equally important because it determines how strongly those global price movements are transmitted into the domestic economy. A stable currency can absorb part of an international price increase, while depreciation can amplify it.
For government, the September figures offer both reassurance and a warning. Inflation remains dramatically lower than it was during the recent crisis, supporting the argument that macroeconomic stabilization has made significant progress. At the same time, two consecutive monthly increases mean authorities cannot treat the battle against inflation as finished.
That balance is likely to shape official messaging around the new numbers. The increase from 5.0 percent to 5.2 percent is small in absolute terms and does not represent a return to the severe inflation experienced in previous years. It does, however, confirm that the direction has changed since July.
The Ghana Statistical Service will continue publishing monthly data that will show whether September was part of a gradual normalization toward the central bank’s target band or the beginning of a more persistent acceleration. October and November readings will be particularly important because they will capture additional effects from energy prices, domestic services and seasonal movements in food markets.
Businesses and investors will also compare those figures with interest-rate decisions and currency performance. If inflation continues moving higher while remaining within or near the central bank’s target, the Bank of Ghana may decide that its current policy stance remains appropriate. A sharper rise could delay any future easing and keep borrowing costs elevated for longer.
For households, the practical question is simpler: whether the cost of everyday goods and services is beginning to rise more quickly again. The September numbers suggest some acceleration, but the scale remains modest. Food inflation is still contained relative to previous years, while the more significant pressure is now coming from non-food goods and services.
That composition means Ghana’s inflation challenge has changed rather than disappeared. The crisis period was characterized by very high headline inflation, rapid currency depreciation and severe increases in food and imported prices. The current environment is one of much lower overall inflation but gradually increasing domestically generated price pressures.
The next several monthly releases will determine whether that transition remains manageable. If inflation settles around the Bank of Ghana’s target range, the September rise may ultimately be viewed as part of a normal return from unusually low levels. If non-food and services inflation continue accelerating rapidly, policymakers may face a more difficult decision about how long to maintain restrictive monetary conditions.
For now, Ghana enters the final quarter of 2026 with annual inflation at 5.2 percent, still below the central bank’s 6 percent to 10 percent target band but higher than it was in July and August. The country has retained much of the progress achieved during the past year, but the latest figures show that the direction of travel has shifted and that keeping inflation under control will require continued attention to domestic costs, energy prices, the cedi and fiscal policy.